Fix the following errors:
Request a Brochure
Learn, explore and unleash your inner chef.
What are the new requirements of SMA?
The Basel Committee on Banking Supervision (BCBS) started consultation on the Operational Risk capital calculation in October 2014. Following the first round of consultations, changes were made to the proposal and a second consultation was held in March 2016. The final requirements are due to be published by the end of the year.
Speaking at the Operational Risk Europe 2016 Conference in London on 14th of June, the Chair of the Working Group on Operational Risk for BCBS, Mitsu M. Adachi, reiterated that the SMA is a proxy-based measurement approach that eliminates the business-line based calculation and the internal model approach. It relies on a business indicator (BI) and a progressive coefficients structure, and it proposes that the internal loss experience enters the calculation for the larger banks.
How will the SMA impact ICAAP and other internal processes?
This has been a point of discussion during the consultation process and one that has sparked some debate amongst practitioners. The concern from the banking sector was primarily
around the ‘disappearance’ of the more advanced risk measurement and modelling for the projection of losses and severe risk exposure. It is important to remember that the proposed SMA is for the calculation of Pillar I (minimum capital requirement) and the ICAAP is stretching into Pillar II, which encourages firms to develop and use better risk management techniques in monitoring and managing their risk. In this context, analytics and modelling still have an important role to play in risk management.
How will the SMA impact operational risk as a whole?
It is difficult to comment on this at this stage as we are still waiting for the final publication. The driver for replacing the current set of Operational Risk capital calculation approaches with a single SMA approach was the need for simplicity and comparability. This need for simplicity and comparability spans across risk types—not only operational risks—with revised rules being implemented for all. The challenge banks face is maintaining the current level of analytical and modelling resources when it does not support Pillar I. It is important for us all to remember that analytical and modelling approaches are valuable for risk measurement and management purposes and in validating the adequacy of the capital held under Pillar II. The key is to ensure that the analytical efforts do not disappear with the implementation of the SMA.
A benefit of the current consultation, which is rarely mentioned, is that BCBS is planning to publish guidance on Operational Risk losses by the end of the year. This is to support the consistent application of the formulae, which currently require the internal loss experience to enter the calculation for larger banks. Hopefully the SMA will help achieve clarity and consistency on this subject.
What are the main challenges ahead and how can these be addressed?
The main challenge that BCBS faces is addressing the discontent expressed by large European banks with the increased capital requirements as a result of the changes proposed. On 16 September Bloomberg reported that “regulators from countries including Germany and Italy told the BCBS that proposed changes to how banks assess credit, market and operational risks must be scaled back and slowed down”. This discontent is supported by the fact that BCBS stated intention was to simplify and standardise not to significantly increase capital requirements.
The main challenge for banks, as is generally the case with changes in regulation, is the implementation timescale. First and foremost, it will be important to understand how much of the feedback received has been taken into account. The responses to the consultation highlighted a number of concerns that appeared as recurrent themes across the industry, internationally. It is usual for BCBS to request implementation of final rules two years after publication, which would mean implementation by the end of 2018. Banks should start parallel running their current approach and the new SMA once the rules are published to ensure all processes are in place and any difficulties can be discussed with the regulator ahead of the compliance date.
What would you like to achieve by attending the 7th Annual Operational Risk Management Forum Conference?
I look forward to hearing the different perspectives and insights of the speakers and, more generally, speaking with other attendees. The topics of SMA, capital, modelling and Cyber risk are timely and the international nature of the speaker line-up will be valuable in gaining a broader perspective.
Ahead of the 7th Annual Operational Risk Management Forum, read here an interview with Mrs. Simona Fionda, Head of Operational Risk at Metro Bank about the new requirements of SMA and how the SMA will impact operational risk as a whole.
Practical Insights From:
-
Craig Ivey, Head of Operational Risk Appetite and CapitalRBS
-
Marike Dokter, VP Head of Operational RiskBarclays
-
Ben Jervis, COO, Prime ServicesCredit Suisse
-
Michael Grimwade, International Head of Operational RiskMitsubishi UFJ Securities
-
Sophie Rutherford, Head of Operational Risk, EMEAState Street
-
Peter Mitic, Head of Operational Risk Methodology UKSantander
About the conference:
This marcus evans event will give companies the best practices and strategies to begin to implement the SMA and assess the impacts it will have on both internal modelling and operational risk management. They will discover and understand the major challenges on the horizon, including the move to the SMA and cyber and IT risk. They will gain an advantage over competitors by hearing from experts that will provide both insight and innovation in dealing with operational risk frameworks.
The 7th Annual Operational Risk Management Forum will take place from the 21st until the 23rd of November 2016 in London, UK.
Copyright © 2016 Marcus Evans. All rights reserved.
Previous Attendees Include
- RBS
- Investec
- Allied Irish Banks
- Rabobank
- SNS Reaal
- Tesco Bank
- Emirates NBD
- Bank of Ireland
- BNP Paribas
- BBVA
- Deloitte
- HSBC Handelsbanken
- LBBW
- J.P. Morgan
- Standard Chartered
About the speaker:
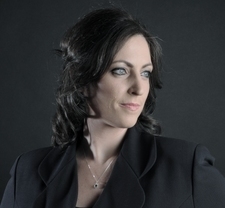
Simona is Head of Operational Risk at Metro Bank, where she is also responsible for Information Security, Cybercrime, incident management and business continuity.
Prior to joining Metro Bank, Simona spent 13 years at Barclays in roles spanning all three lines of defence, from operations and marketing to Operational Risk management and risk auditing.
Throughout her career she has held various global roles, which have involved defining Group-wide Operational Risk reports from a new system of records and defining and launching the Group-wide Operational Risk curriculum.
Simona has acted as Group-wide change programmes liaison for Operational Risk in initiatives such as the TRANSFORM strategic review and the Operational Risk Functionalisation, re-defining the framework and implementing a new system of records for Operational Risk. Her risk-management expertise ranges from framework definition and application in an existing business to M&A activities and change programmes in both UK and international environments.
Simona is a professionally qualified risk manager and regularly speaks at international conferences. She is a member of the Professional Standards & Certification Committee and an examiner for the International Diploma at the Institute of Risk Management. In addition to her risk management qualifications, Simona has degrees in Business Administration and in Business in Europe, and she is a Six Sigma and Prince 2 qualified professional, as well as a qualified financial adviser.
How will the SMA impact operational risk as a whole?
An interview with MetroBank
Simona Fionda, Head of Operational Risk at Metro Bank
